

Why a financial plan is not the same as a budget
Many people equate having a budget with having a financial plan. The two are related but not interchangeable. A monthly budget tracks income and expenses over a short period, usually one month. It tells you whether you can afford your bills and whether you are spending more than you earn.
A financial plan operates on a much longer horizon. It asks where you want to be financially in five, ten, or thirty years, and then maps out the decisions and behaviors that get you there. A budget answers the question of how to manage money this month. A financial plan answers what you are managing it for.
The confusion matters because people who only budget often feel financially responsible yet still find themselves unprepared for retirement, uninsured against major risks, or unable to handle a financial emergency. Without a plan, individual financial decisions tend to be reactive rather than coordinated.
Start with one page
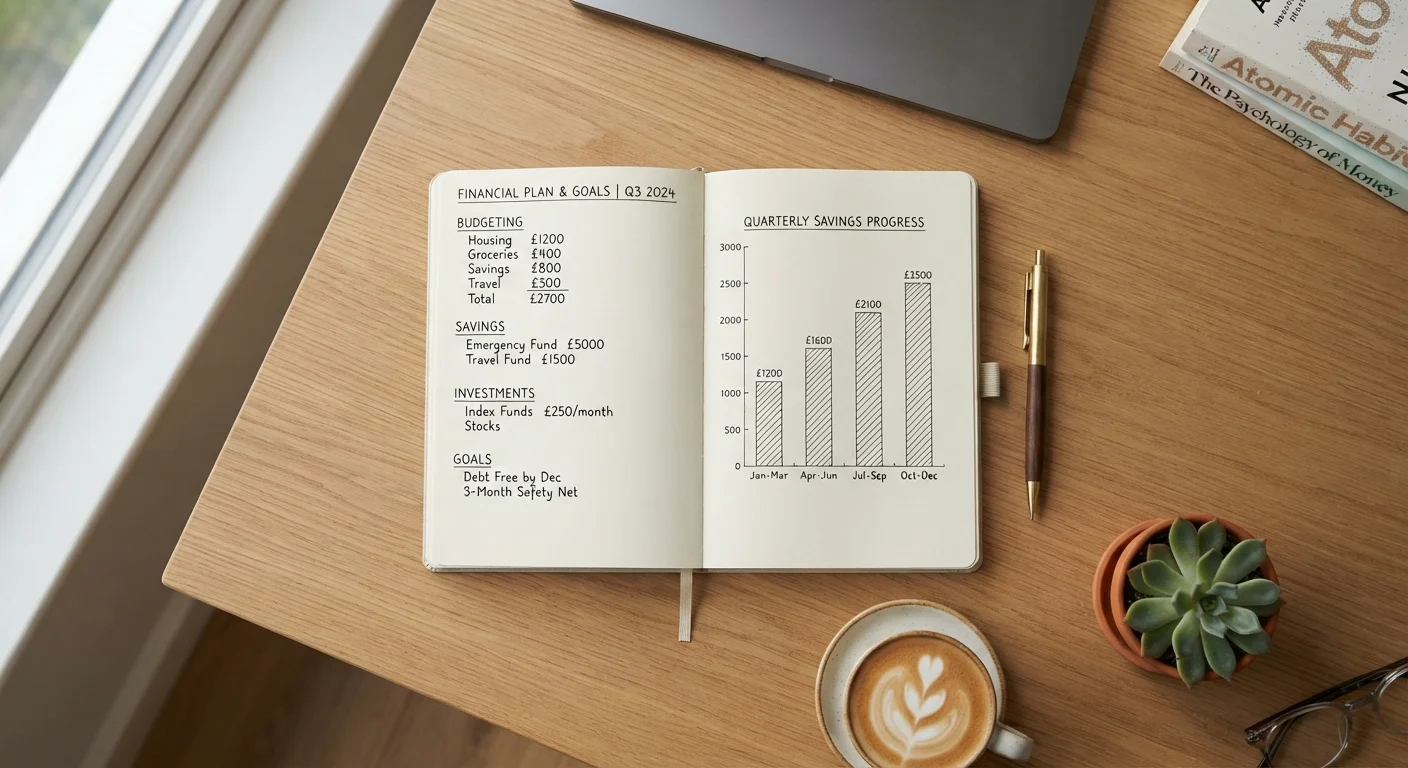
A financial plan does not need to be a formal document. A single page listing your net worth, monthly cash flow summary, and two or three specific financial goals with target dates is more useful than no plan at all. You can expand it as your situation grows more complex.
What a financial plan actually covers
A complete financial plan typically addresses six areas:
- Goals: specific, time-bound targets such as buying a home in seven years, paying off student loans, or retiring at 65.
- Net worth: a snapshot of everything you own minus everything you owe, which tells you your actual financial position today.
- Cash flow: income, fixed expenses, variable spending, and how much is available to save or invest after obligations are met.
- Insurance and risk: protection against events that could derail financial progress, including health, disability, life, and property coverage.
- Investments: a strategy for growing money over time, including retirement accounts and other savings vehicles, appropriate to your timeline and comfort with risk.
- Retirement and estate: projections for how much you will need to stop working and, eventually, a plan for how your assets will be handled.
Not every plan covers all six areas in equal depth. Someone in their twenties with few assets may focus primarily on debt, cash flow, and starting retirement contributions. Someone in their fifties will weight retirement income planning more heavily. The structure adjusts to the individual.
For a fuller picture of how these areas connect, see the complete guide to financial planning.
Why most Americans don't have one
Surveys conducted by financial industry research groups consistently find that fewer than half of American adults have a written financial plan. Several practical reasons explain the gap.
Less than 33%
Americans with a written financial plan
Research from the Certified Financial Planner Board of Standards has found that fewer than one in three American adults has a written financial plan.
56%
Adults unable to cover a $1,000 emergency
A Bankrate survey found that a majority of U.S. adults could not pay for a $1,000 unexpected expense from savings alone, reflecting a widespread absence of planned financial buffers.
Many people believe financial planning is for wealthier households or is too complicated to do without professional help. Others assume a plan is unnecessary when money feels tight, reasoning that there is nothing to plan with. Both assumptions are inaccurate. A financial plan for someone carrying credit card debt and living paycheck to paycheck is, if anything, more useful than one built in comfortable circumstances, because the stakes of uncoordinated decisions are higher.
Time is another barrier. Building a plan requires gathering financial information, setting goals, and making decisions that most people find uncomfortable to confront. Avoidance is easier in the short term, though it tends to be costly over years.
A related problem is vague intentions substituting for actual plans. Wanting to "save more" or "pay off debt someday" is not a plan. Financial goal-setting mistakes that skip timelines, specific amounts, or milestones leave intentions without traction.
How to start building one
A financial plan does not need to be long or sophisticated to be useful. A starting point accessible to most people involves three steps.
First, calculate your net worth. List your assets (checking and savings accounts, retirement accounts, property) and your liabilities (mortgage, auto loans, credit card balances, student loans). Subtract liabilities from assets. The number, whether positive or negative, is your baseline.
Second, document your cash flow. Write down your take-home income and every regular expense. Identify what is left after necessities and minimum debt payments. That figure determines how much is available to direct toward goals.
Third, state at least one concrete goal with a dollar amount and a date. "Save $10,000 in an emergency fund within 18 months" is actionable. That specificity lets you work backward to a monthly savings target and evaluate whether your current cash flow supports it.
From there, the plan grows by adding more goals and addressing the other components over time. The step-by-step process for building a long-term financial plan walks through each stage in detail. For practical tools on organizing spending as part of that process, the budgeting basics hub and a complete overview of personal finance budgeting are useful companions.
This article is for general informational and educational purposes only. It is not personalized financial, tax, or investment advice. Consult a licensed financial professional for guidance specific to your situation.


