

What zero-based budgeting actually means
Zero-based budgeting starts with a straightforward rule: income minus all assigned categories equals zero. Every dollar you expect to receive in a given month gets a label before the month begins. Groceries, rent, a car payment, a Roth IRA transfer, a savings goal for a vacation, an emergency fund deposit. All of them count. When you add every assignment up and subtract the total from your monthly income, the result should be zero.
This is where many people misread the method. The zero does not mean your bank account reaches zero. It means no dollar is unaccounted for. A dollar sitting in your checking account without a purpose is, in zero-based terms, a dollar you have not yet budgeted. That ambiguity is what the method is designed to eliminate.
Compare this to a simpler approach described in building a household budget from scratch, where many people start by listing fixed expenses and leaving the rest flexible. Zero-based budgeting goes further: even the flexible remainder must be divided and named.
What the method requires each month
The monthly process has three distinct phases: planning before the month, tracking during the month, and reconciling at the end.
Planning before the month
Before the first day of any new month, you list your expected income. If you are salaried, this is straightforward. If your income varies, you work from your lowest reliable estimate. Then you list every category you expect to spend in, plus every financial obligation: savings, debt minimums, investment contributions. You assign dollar amounts until income minus assignments equals zero.
This is where reviewing past spending proves useful. Your last two or three months of actual transactions will show you which categories you consistently underestimate, often groceries, home supplies, or irregular bills that do not arrive every month.
Tracking during the month
A budget you write once and ignore is not zero-based budgeting in practice. You need to record spending against categories as it happens, or at minimum every few days. When a category runs low or runs out, you have a decision to make: stop spending in that category or move dollars from another category to cover it. Either choice is valid. What is not valid is ignoring the overage and hoping it balances out.
Build a buffer category into your plan
Label a small category 'buffer' or 'miscellaneous' and assign it $50 to $100 each month. This absorbs small unexpected purchases without forcing a category adjustment every time a minor expense appears. It does not replace an emergency fund; it handles the minor friction of everyday life.
Reconciling at month-end
At the end of the month, any unspent dollars in a category do not disappear. You decide where they go: carry them into next month's version of the same category, move them to savings, or apply them to debt. This deliberate reassignment is what separates zero-based budgeting from simply hoping for a surplus.
Categories that people commonly forget
The method breaks down most often when categories are missing, not when they are over or underfunded. Several expenses catch budgeters off guard because they do not arrive monthly.
- Annual or semi-annual insurance premiums
- Vehicle registration and inspection fees
- Medical copays and prescription refills
- Home maintenance (plumbing, appliance repair, seasonal work)
- Clothing and school supplies for families with children
The standard approach is to estimate each irregular expense annually, divide by 12, and assign that monthly amount to a dedicated category. When the bill arrives, the money is already set aside. Setting realistic limits for these categories takes practice; your first month's estimates will rarely be exact, and that is expected.
33%
Americans with a written monthly budget
Gallup polling has consistently found that roughly one-third of U.S. adults maintain a detailed household budget.
~$1,800
Average unplanned annual spending per household
Research from the U.S. Bureau of Labor Statistics consumer expenditure data shows irregular and miscellaneous expenses represent a material share of annual household outflows.
How zero-based budgeting differs from the envelope method
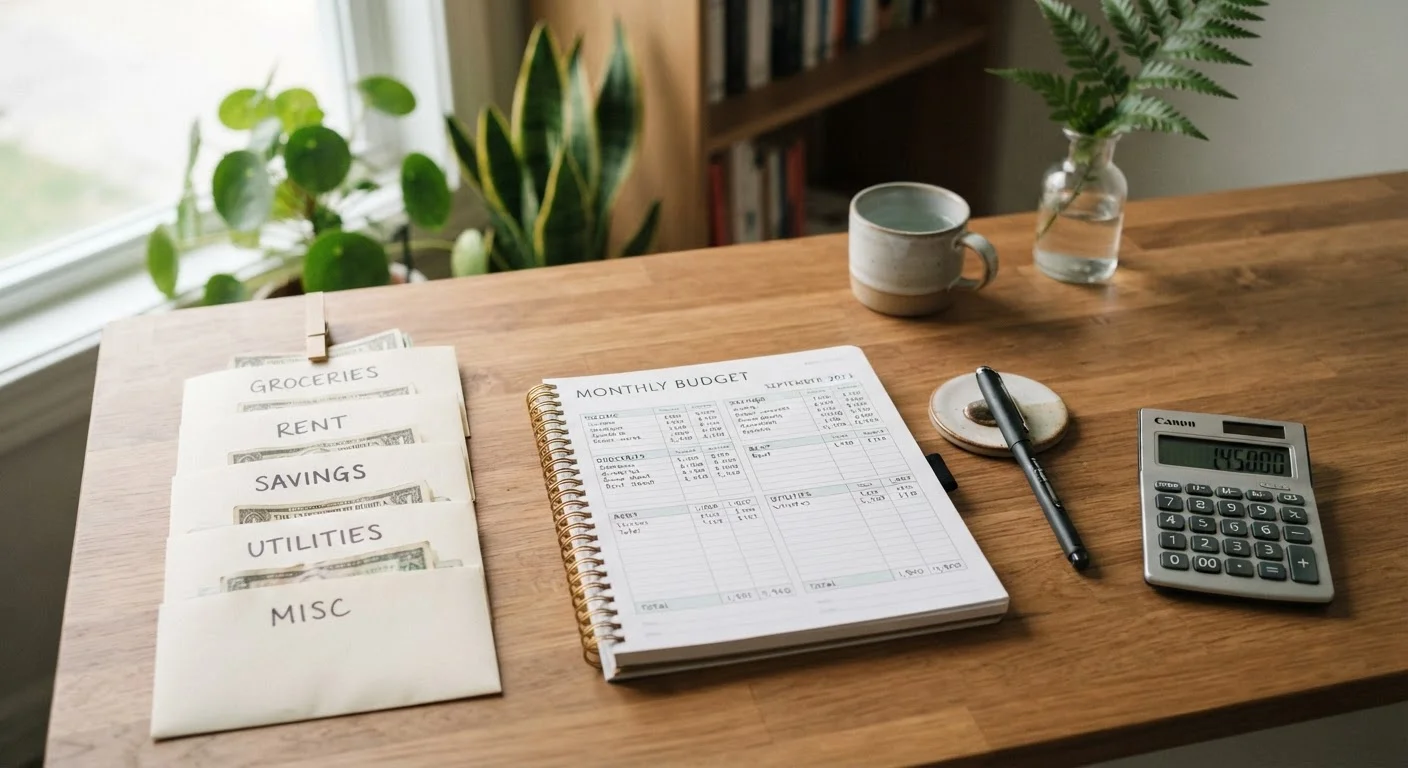
Both methods assign spending limits to categories in advance, and both require adjusting when you overspend a category. The structural difference is in mechanics. The envelope method, even in its digital form described in envelope budgeting without cash, separates money physically or virtually into discrete pools before you spend. Zero-based budgeting is a planning and tracking system; it does not require separate accounts or transfers, only accurate records of what has been assigned and spent.
Some people combine the two: they use zero-based logic to set their monthly plan and envelope mechanics to enforce category limits. This works well for categories where overspending is a recurring problem, such as dining out or entertainment.
The common thread is that both methods require active management. Passive budgeting, where you check your balance occasionally and assume things are fine, is not compatible with either approach.
This article provides general financial education and is not personalized financial advice. Consult a qualified financial professional before making decisions specific to your financial situation.


