

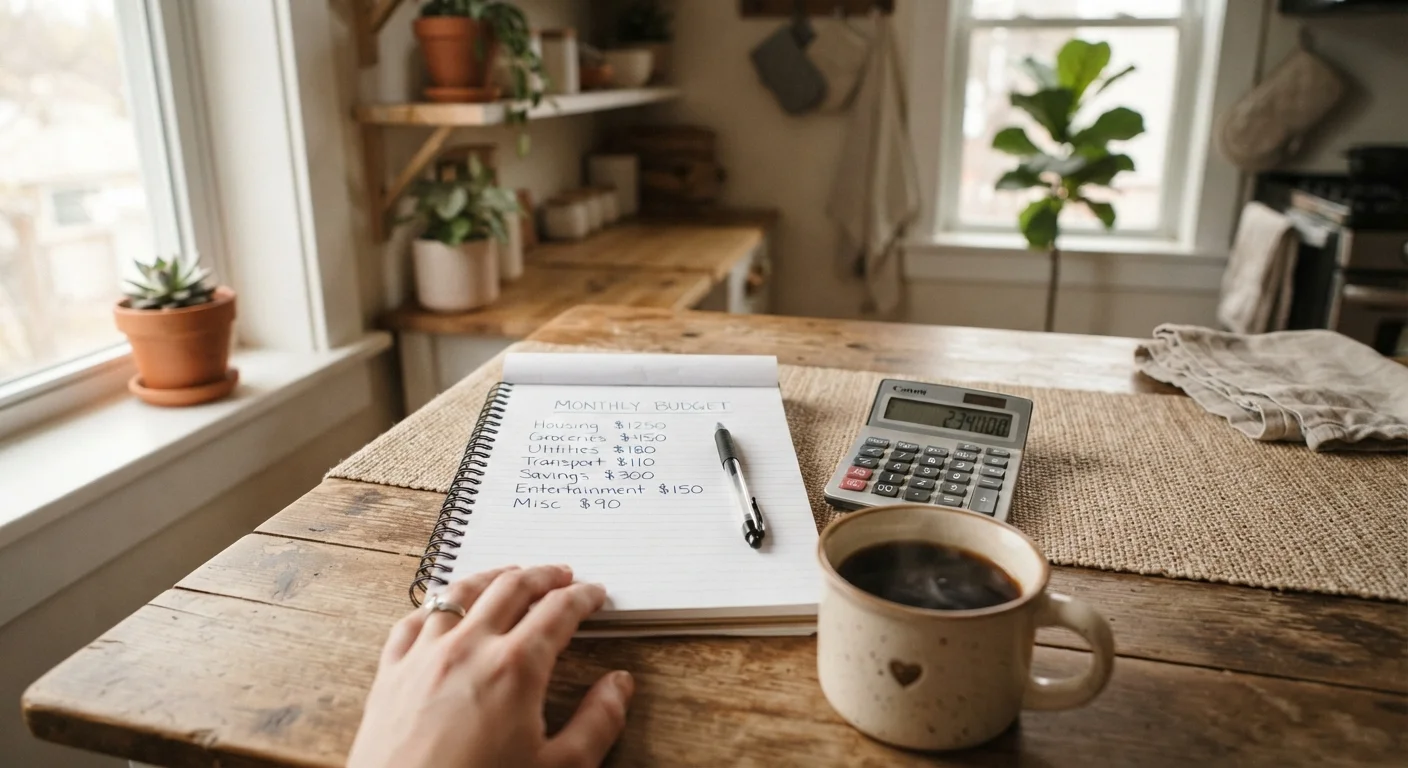
What you need before you start
A household budget is a plan that matches money coming in against money going out. Building one from scratch takes an honest look at both sides, and that requires a few concrete materials before you write a single number.
What you will need
Bank and credit card statements
Provides an accurate record of what you actually spent across all categories over the past 90 days.
Spreadsheet software
Lets you enter income and expense categories, run totals automatically, and adjust numbers without rewriting everything.
Budgeting app
Automates transaction categorization and tracks spending against your limits in real time.
Calculator
Useful for converting annual or irregular costs into monthly equivalents.
If your income varies month to month because you freelance, work hourly shifts, or receive irregular commissions, use the lowest monthly take-home amount from the past six months as your baseline. A budget built on a low estimate is safer than one built on an optimistic average. For a broader view of budgeting methods and frameworks, see our complete budgeting overview.
Building the budget step by step
Follow these steps in order. Each one builds on the last, and skipping ahead tends to produce numbers that look tidy on paper but collapse in practice.
Calculate your real monthly take-home income
Write down every source of after-tax income your household receives in a typical month. This includes wages, salaries, side income, child support, or any other regular deposit. Use the amount that actually hits your account, not the gross figure on your offer letter. If any income source is irregular, use the six-month average as a conservative estimate.
List every fixed expense
Fixed expenses are obligations that stay the same amount each month: rent or mortgage, car loan payments, insurance premiums, and minimum debt payments. Write each one down with its exact monthly amount. These are non-negotiable line items in your budget and must be covered before any other category is funded.
Estimate variable expenses from your statements
Variable expenses change month to month: groceries, gas, dining out, clothing, personal care, and entertainment. Pull your last three months of bank and credit card statements and calculate a monthly average for each category. Do not guess; let your actual spending history set the starting numbers. Categories where your spending fluctuates widely may need a slightly higher estimate to avoid constant shortfalls.
Common variable categories to include:
- Groceries and household supplies
- Transportation (gas, parking, tolls, public transit)
- Dining and takeout
- Personal care (haircuts, pharmacy items)
- Entertainment and streaming
- Clothing
- Medical co-pays and out-of-pocket costs
Account for irregular and annual expenses
Irregular expenses are the most common budget-breaker because they are easy to forget until they arrive. Make a list of every expense you pay less than monthly: car registration, homeowners or renters insurance (if paid annually), holiday gifts, vacation costs, school supplies, and annual subscription renewals. Add up the full year's total and divide by 12. That monthly figure needs its own budget line, and the money should move to a separate savings account each month so it is available when the bill arrives.
Subtract total expenses from total income
Add up all your fixed expenses, variable expense averages, and your monthly irregular-expense contribution. Subtract that total from your monthly take-home income. A positive result means you have room to increase savings or pay down debt faster. A negative result means your current spending exceeds your income, and you need to adjust before the budget is usable.
If the result is negative, work through your variable categories first. Fixed expenses are harder to change quickly. Look for variable categories where your average spending is meaningfully above what you actually need, and set a lower target for those lines.
Assign a savings and debt repayment amount
After your expenses are covered and the budget balances, decide how much to direct toward savings and any debt above the minimum payments. Even a small, consistent amount moving to savings builds a financial buffer over time. If you carry high-interest debt, prioritizing additional payments above the minimum can reduce the total cost of that debt. For more on this balance, managing savings alongside debt involves tradeoffs worth understanding before you allocate.
Track your spending and adjust after 30 days
A first budget draft is rarely accurate. Spend the first month recording every purchase against your categories and compare actuals to targets at month's end. Expect some categories to be off. The goal is not a perfect budget in month one; it is a budget that gets more accurate each month as you calibrate the numbers to your real patterns. After three months of adjustments, most households have a budget that reflects how they actually live rather than how they think they live.
Once your first draft is complete, compare it against a structured framework. The 50/30/20 rule divides take-home pay into roughly 50% for needs, 30% for wants, and 20% for savings and debt repayment. It does not fit every household perfectly, but it gives you a reference point for spotting categories that are out of proportion.
If you prefer a method that accounts for every dollar individually, zero-based budgeting assigns a specific purpose to each dollar of income before the month begins. Both approaches work; the one you will actually use consistently is the right one for your household.
Common pitfalls and how to avoid them
Most budgets fail for one of two reasons: they are too tight to live with, or they omit categories that reliably appear. Setting limits below what you actually spend does not make the expenses go away; it just means your plan breaks the first time you fill a gas tank or buy a birthday gift.
Spending limits that are genuinely livable matter more than limits that look impressive. If your dining-out budget is $50 but you consistently spend $200, adjust the target and reduce something else instead of abandoning the budget entirely.
The other common gap is irregular expenses. Annual subscriptions, vehicle registration, holiday spending, and back-to-school costs do not appear every month, but they are predictable. Add up your known annual irregular expenses, divide by 12, and set that amount aside each month into a separate savings buffer. Your budget categories also tend to shift as your life circumstances change; spending priorities look different at different life stages, so revisit your structure after major changes like a new job, a new child, or a move.
Once your budget is running, a budgeting app can make tracking easier. Setting up a personal budget app for the first time takes less time than most people expect, and it automates much of the month-to-month tracking. For a cash-free household, the envelope method adapted for digital spending applies the same spending-limit logic without physical bills.
This article is for informational purposes only and does not constitute personalized financial advice. For guidance specific to your situation, consider consulting a qualified financial professional.


